 Buy Now, Pay Later use reached 16% of U.S. adults in 2025, up from 10% in 2021. New analysis from the Federal Reserve shows that these short-term installment plans now cover far more than discretionary shopping. Clothing and accessories remain the leading category, used by 49% of BNPL users. Yet 20% reported financing groceries or food delivery.
The expansion into everyday expenses matters because food is normally consumed long before the debt used to buy it disappears. The Federal Reserve found that electronics were financed by 32% of users, furniture or appliances by 26%, travel by 19%, and medical or veterinary expenses by 8%. These figures suggest BNPL has evolved from a checkout feature for occasional purchases into a broader form of consumer credit.
Why Does Paying in Four Feel Easier?
A common BNPL arrangement divides a purchase into four installments. The Consumer Financial Protection Bureau explains that payments are often made every two weeks, with many plans charging no interest when payments are made as required. Compared with paying the entire price at checkout, the smaller individual amounts can feel more manageable.
Consumers have different reasons for choosing the option. Federal Reserve survey data shows that 32% of users primarily wanted to spread out payments, while 30% said BNPL was the only way they could afford the purchase. Another 16% primarily wanted to avoid interest charges.
When Small Payments Become a Bigger Obligation
The risk becomes harder to see when several plans overlap. A $25 installment may look minor by itself. Five or six scheduled payments from different purchases can create a much larger claim on the next paycheck.
Research from the Consumer Financial Protection Bureau found that more than three-fifths of BNPL borrowers in its 2022 dataset held multiple simultaneous loans at some point during the year. One-third borrowed through multiple providers. That fragmentation can make the total amount owed less obvious than a single credit-card balance.
Financial strain appears especially important when BNPL pays for necessities. The Federal Reserve found that 45% of people who financed groceries or food delivery said their main reason was that BNPL was the only way they could afford the purchase. Among grocery and food-delivery users, 43% had either paid a late fee or incurred an overdraft or insufficient-funds fee related to BNPL use.
Flexibility or a Sign of Budget Stress?
Installment credit can provide useful flexibility when the purchase fits comfortably within upcoming income. Consumers can make that distinction by looking beyond the size of the next payment.
- Add every BNPL payment due during the month before making another purchase.
- Ask whether the item could be bought without borrowing.
- Check account balances before automatic payments are scheduled.
- Avoid using new installments simply to cover routine gaps between income and expenses.
BNPL itself does not automatically signal financial trouble. The more important question is what it finances and whether repayment depends on money that is already stretched. When groceries repeatedly become installment debt, convenient payment flexibility may be turning into chronic reliance on short-term credit.
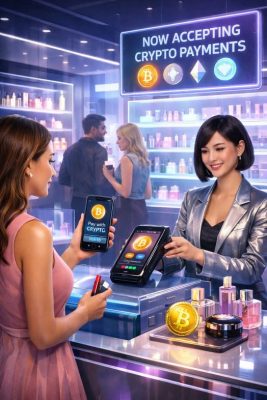 Global oil prices continue to influence inflation, shipping costs, and household spending, creating ripple effects that reach industries far beyond energy. As consumers adjust their budgets during periods of economic uncertainty, retailers are exploring new ways to improve convenience and maintain customer engagement, including the adoption of cryptocurrency payments.
 AI-powered investment platforms analyze market trends, predict financial movements, and make data-driven decisions. This ensures that social impact funds are growing and being strategically reinvested into critical social programs. The ability to automate trading helps investors optimize their portfolios while ensuring a steady flow of funds into essential services.